
You buy a property and also deposit cash in your bank account. The Income Tax department treats both as unexplained income and asks you to file your income tax return. What do you do?A resident of Jaipur attracted the Income Tax Department’s attention after purchasing a property and depositing cash in his bank account without filing an income tax return.
What the case is about
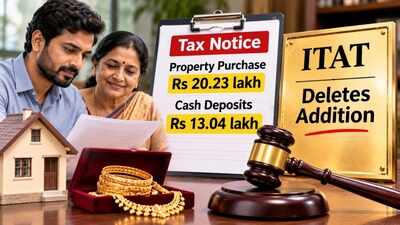
A man purchased a property worth Rs 20.23 lakh and deposited Rs 13.04 lakh in cash into his bank account. The department had received information about these transactions and began proceedings to investigate the source of the funds used for the investment and cash deposits.During the proceedings, the taxpayer filed his income tax return, declaring an income of Rs 2,14,997. However, the Assessing Officer (AO) treated both the property investment of Rs 20,23,778 and the cash deposits of Rs 13,04,900 as unexplained. This resulted in additions of Rs 33,28,678, or approximately Rs 33.29 lakh, to the man’s income.The person contested the assessment before the Commissioner of Income Tax (Appeals). The appellate authority removed the addition relating to the property purchase but retained the Rs 13,04,900 addition for unexplained cash deposits.He subsequently approached the Jaipur Bench of the Income Tax Appellate Tribunal (ITAT), challenging the amount that continued to be treated as unexplained income.In an order dated October 6, 2026, ITAT Jaipur decided the matter in the man’s favour and deleted the addition of Rs 13,04,900 relating to the cash deposits. The addition concerning the property investment had already been removed by the Commissioner of Income Tax (Appeals).
Why did ITAT rule in favour of the assessee?
The person’s counsel told ITAT Jaipur the assessee’s mother had sold her old gold jewellery and given her son Rs 16 lakh in cash. A registered valuer had assessed the jewellery’s value at Rs 18,36,230 in 2011.The Assessing Officer was not satisfied with this explanation because the documents relating to the jewellery sale did not list the individual gold items. The cousel countered that old jewellery is commonly sold in the trade on the basis of its aggregate weight, without each item being separately described on the invoice.The AO had also raised questions about the difference between the total weight recorded in the valuation report and the quantity of jewellery sold. Responding to this objection, the counsel submitted that the person’s mother had sold 642.300 grams of jewellery for Rs 16,10,567 and subsequently gifted Rs 16 lakh to her son.To support the explanation, the person relied on a notarised gift deed bearing the signatures of two witnesses and the valuation report prepared by the registered valuer. The tribunal also noted that the man had deposited a total of Rs 16,05,000 into his bank account between February 4 and March 31, 2012.After examining the arguments and supporting documents, ITAT Jaipur accepted the man’s explanation for the source of the cash deposits.The tribunal observed: “This gift is from the mother only which is within the relatives as defined in Section 2(41). Further the assesee’s mother in her old age gifted part of the amount from sale of her gold jewellery given as gift to the assessee, which cannot be doubted, since the same is supported by valid notarised Gift Deed with two witnesses and value of the jewels were determined by Registered Valuer. Thus the addition made by the AO is liable to be deleted.”On this basis, the tribunal removed the addition of Rs 13,04,900 that had been made for unexplained cash deposits.Chartered Accountant Varun Singhal told ET that taxpayers seeking to explain the source of funds through a gift should take certain precautions. They should establish where the donor obtained the money instead of relying only on documentation confirming that the gift was made. It is also important to retain documents created at the relevant time, such as the gift deed, valuation report and jewellery-sale invoice.Taxpayers should maintain a clear documentary trail connecting the gift to the subsequent bank deposits, ensuring that the dates and amounts can be matched. Where available, the donor’s bank statements and other financial records should also be preserved.







Leave a comment